An annuity is an insurance contract often used for long-term income, while a CD is a bank deposit that earns interest for a set time.
Imagine you have $20,000 that you want to save. You want your money to grow, but you are not sure where to put it. A friend tells you about a CD. Another person suggests an annuity. Both can help you save money, but they work in very different ways.
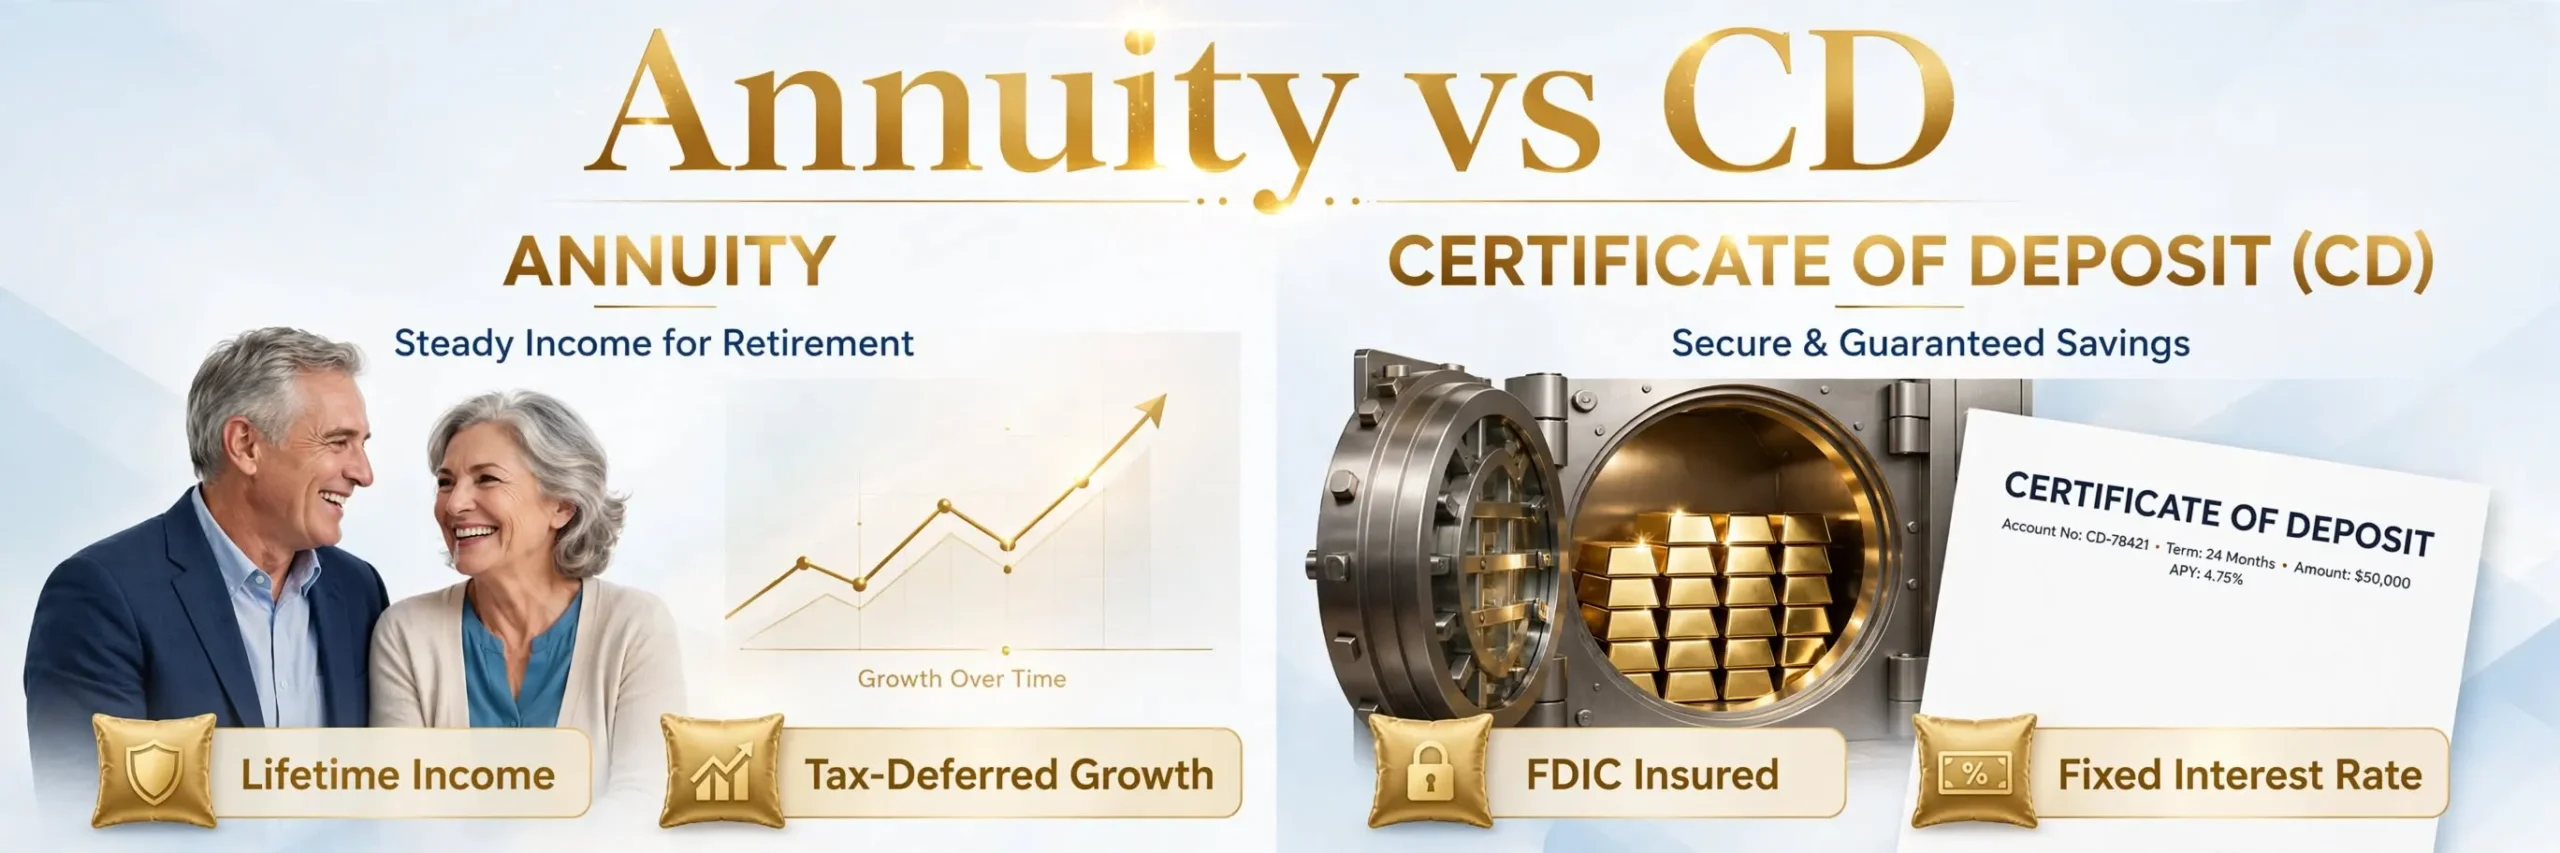
An annuity is a contract with an insurance company. It can provide income now or later and may offer tax-deferred growth. A CD, or certificate of deposit, is a bank deposit. You place money in the CD for a fixed period, and the bank pays you interest.
People search for annuity or CD because both can be used for saving and income goals. The main confusion is that they can look similar when people compare interest rates and safety. This guide explains annuity or CD in simple terms. It covers their differences, uses, history, examples, and common mistakes.
Pronunciation
Annuity
- US: /əˈnuːəti/
- UK: /əˈnjuːəti/
CD
- US: /ˌsiː ˈdiː/
- UK: /ˌsiː ˈdiː/
The two choices may both involve saving money, but their structure and purpose are different.
Difference Between Annuity or CD
1. Basic Meaning
An annuity is a contract with an insurance company. A CD is a deposit account offered by a bank or credit union.
Example 1: Maria buys an annuity for future retirement income.
Example 2: John puts $10,000 into a one-year CD.
2. Main Purpose
Annuities are often used for long-term financial and retirement goals. CDs are commonly used to save money for a fixed period and earn interest.
Example 1: A retiree may use an annuity for regular income.
Example 2: A saver may use a CD for money needed after one year.
3. Provider
An annuity comes from an insurance company. A CD comes from a bank or credit union.
Example 1: Lisa signs an annuity contract with an insurer.
Example 2: Tom opens a CD at a bank.
4. Time Period
A CD normally has a stated maturity date, such as six months, one year, or five years. An annuity can be designed for a much longer period and may provide lifetime income.
Example 1: A CD may mature after 12 months.
Example 2: An annuity may provide payments for life.
5. Income
Annuities can be designed to provide regular income payments. A CD usually pays interest and returns the deposit at maturity.
Example 1: Sara receives monthly annuity payments.
Example 2: Mark receives his CD money when the CD matures.
6. Insurance Protection
A CD at an FDIC-insured bank can generally receive FDIC deposit insurance up to applicable limits. Annuities are not FDIC-insured.
Example 1: A qualifying bank CD can have FDIC protection.
Example 2: An annuity depends on the financial strength and claims-paying ability of the insurance company.
7. Early Withdrawal
Taking money from a CD before maturity can result in an early-withdrawal penalty. An annuity may have surrender charges or other contract costs for early withdrawals.
Example 1: Jane withdraws her CD money early and pays a penalty.
Example 2: Paul withdraws from an annuity during its surrender period and faces a charge.
8. Tax Treatment
Annuities can provide tax-deferred growth. CDs generally pay taxable interest, subject to applicable tax rules.
Example 1: An annuity may allow earnings to grow without current taxation until certain withdrawals or payments occur.
Example 2: Interest from a CD may need to be reported for tax purposes.
9. Fees
CDs are usually simple deposit products. Some annuities can have fees, surrender charges, and other costs.
Example 1: A simple CD may have no monthly account fee.
Example 2: An annuity contract may include insurance or contract-related costs.
10. Complexity
CDs are generally easy to understand. Annuities can be more complex because they come in different forms, including fixed, indexed, and variable annuities.
Example 1: A saver can compare CD terms and maturity dates.
Example 2: An annuity buyer may need to review fees, guarantees, surrender periods, and income options.
Nature and Behaviour of Annuity or CD
Nature of an Annuity
An annuity is an insurance contract. You may pay a lump sum or make several payments. Depending on the contract, the insurer can later provide regular income. Some annuities also offer tax-deferred growth.
Nature of a CD
A CD is a deposit account. You put a fixed amount into it for a set period. The bank pays interest, and you normally receive your principal plus interest when the CD matures.
Also read more about:https://textlinkerpro.com/legos-or-lego/
Why People Get Confused About Annuity or CD
People may confuse them because both can involve a fixed amount of money and interest. Both may also be used by people who want to protect or grow savings.
The key difference is simple:
A CD is a bank deposit. An annuity is an insurance contract.
Their rules, risks, protections, costs, and income features can be different.
Comparison Table
| Feature | Annuity | CD |
|---|---|---|
| Basic type | Insurance contract | Bank deposit |
| Main provider | Insurance company | Bank or credit union |
| Common goal | Long-term income | Short- or medium-term saving |
| Fixed term | Depends on contract | Yes |
| Retirement income | Can provide regular income | Not normally designed for lifetime income |
| FDIC insurance | No | Yes, if eligible and held at an FDIC-insured bank |
| Early access | May involve surrender charges | May involve early-withdrawal penalty |
| Tax treatment | Can offer tax-deferred growth | Interest is generally taxable |
| Complexity | Can be complex | Usually simpler |
| Main protection | Depends on insurer and contract | Deposit insurance may apply |
The Origin of Annuity or CD
The word annuity comes from a Latin word connected with yearly payments. The idea of receiving regular payments has a long history.
The term certificate of deposit describes a certificate or record showing that money has been deposited for a set period. Modern CDs developed as banking products that pay interest on money kept at the institution.
Today, both terms are common in personal finance, but they describe different products.
British vs American English
The words annuity and CD are used in both British and American English.
The main difference is often the term CD. In the United States, CD commonly means certificate of deposit.
In the UK, similar savings products are often described with terms such as fixed-rate savings account or fixed-term deposit, depending on the product.
American example:
“I put my savings into a one-year CD.”
British-style example:
“I put my savings into a fixed-term savings account.”
The exact product name can vary by country.
Which One Should You Use?
There is no single choice that fits everyone.
For a U.S. saver looking for a bank deposit with a fixed term, a CD may fit the goal. Eligible CDs at FDIC-insured banks receive deposit insurance within applicable limits.
For someone planning long-term retirement income, an annuity may offer features that a CD does not, such as periodic income payments. However, the contract terms, costs, surrender period, and insurer’s financial strength should be reviewed carefully.
Common Mistakes
- Mistake: Calling an annuity a bank deposit.
Correction: An annuity is an insurance contract. - Mistake: Assuming every annuity is FDIC-insured.
Correction: Annuities are not FDIC-insured. - Mistake: Thinking every CD can be withdrawn freely.
Correction: Early withdrawal may cause a penalty. - Mistake: Thinking every annuity works the same way.
Correction: Annuities can have different types and features. - Mistake: Comparing only the interest rate.
Correction: Also check fees, access rules, guarantees, taxes, and time periods.
Everyday Usage Examples
In Emails
“I am comparing an annuity and a CD for my long-term savings.”
On Social Media
“An annuity and a CD may both help with savings, but they work in different ways.”
In News
“Investors are comparing CDs with other savings and income products.”
In Formal Writing
“A certificate of deposit is a bank deposit with a stated maturity date, while an annuity is an insurance contract that may provide future income.”
Usage Trends
The terms annuity and CD are widely used in U.S. financial writing.
CDs are common in discussions about interest rates, savings, bank deposits, and short- or medium-term goals. Annuities often appear in discussions about retirement income and long-term financial planning.
Online searches often compare them because people want to understand their differences before putting money into either product.
Metaphors and Similes
Annuity
An annuity can be compared to a steady income stream.
Example:
“Her annuity was like a steady stream of income during retirement.”
CD
A CD can be compared to locking money in a safe box for a set time.
Example:
“A CD is like putting money in a locked box until the maturity date.”
These are simple comparisons, not exact financial definitions.
Connotative Meaning
Annuity
- Positive: steady income, retirement planning, long-term security
- Negative: fees, restrictions, complexity
- Neutral: insurance contract, income product
CD
- Positive: saving, interest, stability
- Negative: limited access, early-withdrawal penalty
- Neutral: bank deposit, fixed term
The connotation can change based on the speaker’s experience and the specific product.
Idioms and Proverbs
There are no major English idioms that directly mean annuity or CD.
However, common money sayings can be used when discussing savings.
“Save for a rainy day.”
Example: “She used a CD as part of her plan to save for a rainy day.”
“A penny saved is a penny earned.”
Example: “He believes in saving money carefully, so he compares CDs before choosing one.”
Literature and Movies
Financial products such as annuities and CDs are not usually the main subjects of classic literature.
However, money, saving, retirement, and financial choices appear in many works.
For example, The Great Gatsby by F. Scott Fitzgerald was published in 1925 and explores wealth and social class in the United States.
A modern financial film is The Big Short (2015), an American movie about the financial crisis. It focuses on complex financial markets rather than CDs or annuities specifically.
Why This Difference Matters
Knowing the difference between an annuity and a CD helps readers understand financial information.
A CD is a deposit product. An annuity is an insurance contract. They can have different protections, costs, tax rules, and access rules.
This difference matters because using the wrong term can create confusion. A person comparing financial products should understand what the product actually is before focusing on its interest rate or possible income.
For English learners, the comparison is also useful. It teaches common financial vocabulary used in banks, retirement planning, and personal finance.
Usefulness in Daily Life
These terms can appear in many real-life situations.
- You may see CD when opening a bank account.
- You may hear annuity during retirement planning.
- You may compare CD maturity dates.
- You may read about annuity income options.
- You may ask a financial professional about fees and penalties.
- You may compare deposit insurance with insurance-company guarantees.
Understanding the terms makes financial conversations easier.
Situational Preference
A CD may be relevant when someone wants a bank deposit with a fixed maturity period and is comfortable keeping the money there until maturity. An annuity may be relevant when someone has a long-term goal and wants an insurance contract that can provide future income. The right product depends on the person’s goals, time period, access needs, taxes, costs, and risk factors. A CD at an FDIC-insured bank may have deposit insurance within applicable limits, while an annuity does not have FDIC insurance.
Possible Questions
Is an annuity the same as a CD?
No. An annuity is an insurance contract, while a CD is a bank deposit.
Is a CD safer than an annuity?
They have different types of protection. Eligible CDs at FDIC-insured banks receive FDIC deposit insurance within applicable limits. Annuities are not FDIC-insured and depend on the insurer’s contractual obligations and financial strength.
Can an annuity provide monthly income?
Yes. Some annuities are designed to provide regular income payments. The payment structure depends on the contract.
Can I withdraw money from a CD early?
Usually, yes, but an early withdrawal may result in a penalty. Check the CD terms before withdrawing money.
Are annuities FDIC-insured?
No. FDIC insurance covers qualifying bank deposits, not annuities.
Do annuities have fees?
Some annuities have fees, surrender charges, or other costs. The details depend on the contract.
What does CD stand for?
CD stands for certificate of deposit.
Conclusion
Annuity or CD comparison is useful because the two products may look similar at first, but they serve different purposes. A CD is a bank deposit that normally holds your money for a fixed period and pays interest. An annuity is an insurance contract that can be designed for long-term savings and regular income.CDs at FDIC-insured banks may receive deposit insurance within applicable limits. Annuities do not receive FDIC insurance. Instead, an annuity depends on the insurance company’s contractual obligations and financial strength. The products also differ in access, taxes, fees, maturity, and income features. A CD may be easier to understand for a fixed savings period. An annuity can have more features and more complex terms. Always read the product details carefully before making a financial decision.

I’m Khadija Zafar, a content writer and blogger. I write simple, engaging articles on English grammar, word meanings, synonyms, antonyms, and vocabulary to help readers improve their English skills.